.

Sunday, May 11, 2014

New Zealand Dollar Rise Threatens Economic Recovery

New Zealand Dollar Rise Threatens Economic Recovery
Having risen nearly 30% against the US Dollar since March, the New Zealand Dollar (NZD or Kiwi) is now close to a 9 1/2 month high. While still far from the record highs of 2008, the currency is already erased a large portion of the losses it racked up since the credit crisis gave way to economic recession.

As part of last Friday’s coverage of the Japanese Yen, we included a chart which compared the performance of the AUD/JPY cross to the S&P 500. Even without calculating the correlation coefficient, a cursory review of the chart revealed an uncanny relationship! Unsurprisingly, it turns out the same relationship also applies to the New Zealand Dollar, whose recent performance closely mirrors US equities.
nzd
In other words, the interplay between risk appetite and risk aversion continues to dominate the forex markets, as traders move to calibrate the split of funds between so-called safe haven currencies and the riskier alternatives, among which the New Zealand Dollar is certainly counted. Much of the rally in the Kiwi, then, represents a correction, as investors acknowledge that the near 50% slide from-peak-to-trough was an overreaction.
Going forward, however, the Kiwi will have to rest on its own feet, as new themes move to the fore of investors’ minds. Specifically, they will begin to look more closely at the New Zealand economy, and demand evidence of a recovery. “Reserve Bank of New Zealand Governor Alan Bollard told a business audience the world has ‘avoided a repeat of the Great Depression. Now, we and the world, appear to be on our way to recovery. New Zealand looks likely to start recovering ahead of the pack.’ ”
At the same time, the most recent economic data showed an economy in freefall, as “New Zealand’s economy shrank for a fifth straight quarter…The economy contracted 2.7 per cent in the January-March quarter.” While forecasts vary, GDP is expected to fall by at least 2.1% in 2009, with a modest pickup expected in 2010. Investors are betting that the recovery will be driven by rising demand for commodities, which will help to buoy New Zealand exports. Once again, this conflicts with the data, which shows an annualized trade deficit of $3 Billion. Despite a fall in imports, the country is still importing more than its exporting. This could be a product of the stronger currency, which all stakeholders agree is not conducive to economic growth. In the end, the economy’s best chance for recovery lies in a resumption of debt-induced consumption and residential construction, the very forces which caused the current downturn. Says Mr. Bollard, “Reliance on past experience of strong house price inflation and easy credit will be untenable.”
Given the uncertain prospects for growth, combined with moderating price inflation, the RBNZ can be expected to hold interest rates at current levels for the near-term. “Bollard will leave the benchmark interest rate unchanged at a record low 2.5 percent on July 30, according to all 10 economists surveyed by Bloomberg.” Based on swap rates, the markets feel similarly, and are pricing a mere 25 basis point hike over the next twelve months. With such a dubious prognosis, one has to wonder whether the Kiwi’s rally is really sustainable.
new-zealand-cpi-inflation2

Canadian Dollar Slated to Outperform Other Commodity Currencies

Canadian Dollar Slated to Outperform Other Commodity Currencies
In the same vein as Monday’s and Tuesday’s posts (covering the New Zealand Dollar and Australian Dollar, respectively), I’d like to use today’s post to look at another commodity currency – the Canadian Dollar. The Loonie, it turns out, has also benefited from the a recovery in risk appetite and concomitant boom in commodity prices; it has appreciated by 7% against the USD in the last month alone, en route to a ten-month high. “All in all, with almost everything going its way these days (besides the crummy weather and the impact on tourism), a return trip to parity – last visited nearly one year ago – doesn’t seem far fetched,” chimes one optimistic analyst.

cad-usd
Like Australia and New Zealand, Canada’s economic fate is tied closely to commodity prices. Simply, as oil and other natural resources have inched closer to last year’s record highs, the Loonie has rebounded proportionately. “Raw materials account for more than 50 percent of Canada’s export revenue. Crude is the nation’s largest export.” Of course, this relationship works both ways. Any indication that the global economic recovery is stalling, and commodities prices would likely tumble, bringing commodity currencies down likewise.
Unlike the Australian Dollar and New Zealand Dollar, the Loonie has never really held much appeal as a carry trade currency. Even at their peak, Canadian interest rates were mediocre, from the standpoint of yield. The current rate is a measly .25%, compared to 2.5% in New Zealand and 3% in Australia. Moreover, while Australia may begin tightening as soon as the fall, “The Bank of Canada committed to keep its key policy rate at the lowest possible level until the spring of 2010,” after voting to hold rates at yesterday’s rate setting meeting. This interest differential could explain why the Aussie has outpaced the Loonie of late.
cad-aud
Another key difference – and potential explanation for the currencies’ recent divergence – is that Australia is considered part of the Asian economic zone, while Canada’s economic fortunes are closely aligned with those of its main trading partner, the US. China, alone, is helping to lift Australia out of recession. The US, meanwhile, is still struggling to find its feet. Hence, it is projected that Canadian GDP will contract by 2.3% in 2009, while Australian GDP may fall by a modest .5%. “When things look bad, you are more likely to sell Canada than the Australian dollar because its economy is moderated by Asian growth,” explains one analyst.
Going forward, this regional differentiation could actually work to the advantage of Canada, which is forecast to grow by an impressive 3% in 2010, compared to 1% growth in Australia. Accordingly, one analyst advises that “Investors should sell Australia’s dollar against Canada’s as a ‘relative commodity play’ because an attempt by China to reign in bank lending on concern it may be creating asset-price bubbles could slow Asian growth…’The Canadian dollar should outperform because it is much more closely linked to a recovery in the U.S.’ “

Risk Aversion Hits Australian Dollar

Risk Aversion Hits Australian Dollar
These days, I feel like you could take that title and substitute pretty much any currency for the Australian Dollar. Let’s face it- the EU sovereign debt crisis has hit a number of currencies extremely hard, as investors have fled anything and everything risky, in favor of the US Dollar, Swiss Franc, Japanese Yen, and Gold.
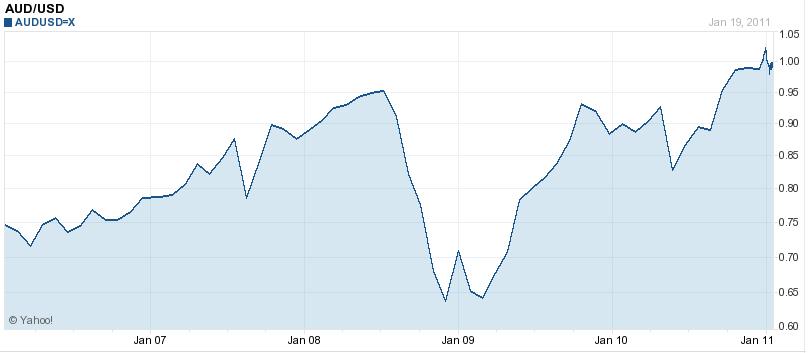
 Still, the Australian Dollar merits special attention, because in the forex markets, it has come to be a symbol of risk-taking. For veritable years, every credit expansion and economic boom has been accompanied by a surge in the value of the Aussie, and 2009 was no exception. As the global economy recovered and risk aversion ebbed, the Australian Dollar rose by more than 40% against the USD. It has been helped in its upward course by Chinese demand for its natural resources and strong interest rates, especially compared to the rest of the industrialized world.
AUD USD 2 Year Chart
 
That the Australian Dollar has already fallen 14% (from peak to trough) against the US Dollar over the last month is less due to economic and monetary factors, however, and more the result of an ebb in risk-taking. “The Australian dollar is considered a barometer of global risk appetite. Its fall reflects the quick change in mood, as Europe’s debt problems and China’s monetary tightening plans cloud expectations for the global economic growth,” summarized one analyst.
 
Specifically, investors are growing increasingly nervous about the viability of the carry trade, of which the Australian Dollar has been one of the primary beneficiaries. Uncertainty surrounding the fiscal problems of the Eurozone has catalyzed a spike in volatility, and investors have responded by rapidly unwinding their carry trade positions. Ironically, this caused a temporary upswing in the Euro, at the expense of the Aussie: ” ‘The euro rally isn’t that people like the euro. Investors have decided they want out of risk.’ The way to remove that risk from portfolios is to pay back the euro loans by selling the Australian dollar.”
 
From another standpoint, the yield advantage associated with holding Australian Dollars is no longer enough to compensate investors for the added risk. After adjusting for inflation, real interest rates in Australia are only about 2.5% (the nominal benchmark rate is 4.5%). This is still 2.5% higher than the benchmark US Federal Funds Rate, but not very attractive if you consider that the Australian Dollar has fallen by more than 2.5% against the US Dollar in several individual trading sessions in May. Moreover, the Reserve Bank of Australia (RBA) is signalling a pause in its rate hikes. If futures contracts are any indication, the Fed and the ECB will raise their respective interest rates before the RBA moves again.
 
Going forward, the consensus is that a sustainable level for the Australian Dollar based on current fundamentals is probably around .75 AUD/USD. However, the Aussie rallied 5% against the US Dollar last week, which suggests that investors still aren’t ready to give up completely: ” ‘The environment is not yet ripe to get truly bearish on the Australian dollar,’ said Commonwealth Bank Strategist Richard Grace. There are positives on the horizon, namely a better outlook for the U.S. and a calming of the Greek crisis, he said. He’s forecasting a return to $0.87.” Personally, I could see the Aussie going either way. Parity probably isn’t on the table anymore, but virtually everything else still is.

New Zealand Dollar Thriving in Obscurity

New Zealand Dollar Thriving in Obscurity
It’s understandable that forex investors basically ignore New Zealand. Its economy is around 10% the size of its neighbor Australia, its currency is less liquid, and spreads are higher. Given that its performance closely tracks the Australian Dollar, meanwhile, why pay it any attention?

NZD AUD 1 year
To be sure, the new currencies from Down Under trade in virtual lockstep, having strayed by only a few cents in either direction from their trading mean over the last year. Since the beginning of May, however, the Kiwi has staged an impressive rally, rising 8% against the Aussie in a matter of weeks. Perhaps, there is something worth analyzing after all!
According to most analysts, the sudden rise is largely a product of risk-appetite. Specifically, as the EU sovereign debt crisis stalls, investors are relaxing, and gradually moving capital back into growth currencies, like the New Zealand Dollar. In fact, the Kiwi recently rose to a one-month high on the same day that Spain successfully completed a bond auction.
For proof of this phenomenon, one need look no further than the close relationship between the NZD/USD rate and US stocks, as proxied by the S&P 500. You can see from the chart below that they have largely tracked each other over the last 12 months. This relationship seems to have intensified over the last few weeks, as the New Zealand Dollar sometimes takes its cues directly from releases of US economic data.
NZD USD 1 year
However, New Zealand economic fundamentals are also playing a role, perhaps even the dominant role. According to one analyst, “The NZ dollar had now recovered nearly all its losses of late May…Domestic fundamentals had contributed relatively more to the NZ dollar’s recent recovery than had the mild improvement in the global backdrop.” Unlike Australia, which has been racked by political disruptions and concerns over an economic slowdown by its largest trade partner (China), New Zealand continues to coast at a healthy pace.
Moody’s forecasts that New Zealand’s economy will expand by 2.4% in 2010, and “assuming a healthy global economy, New Zealand’s recovery should evolve into a self-sustaining expansion during 2011 and 2012.” This should set the stage for near-term rate hikes, beginning with an expected 25 basis point hike on July 29. Analysts project that the benchmark rate will reach 3.75% by the end of 2010, and 5% in 2011. Widening interest rate differentials, combined with the ongoing recovery in risk appetite, could turn the Kiwi into a popular carry trade currency.
Given that the Central Bank of Australia is also projected to further hike rates, it seems the Aussie will join the Kiwi in its upward march, and that the two currencies will continue to trade in lockstep. Options traders might try to construct a low volatility strategy, such as a short straddle or selling covered calls against the pair. For currency traders that prefer the Aussie, meanwhile, the New Zealand Dollar could serve as an attractive hedge.
Then again, it’s possible that both currencies could fade, especially if the EU debt crisis intensifies, and/or the global economic recovery stalls. In short, “The near-term outlook is…uncertain due to prevailing risk aversion that may weigh on the commodity currency universe.”

Tuesday, December 20, 2011

Aussie May Have Peaked in 2010

Aussie May Have Peaked in 2010
When offering forecasts for 2011, I feel like I can just take the stock phrase “______ is due for a correction” and apply it to one of any number of currencies. But let’s face it: 2009 – 2010 were banner years for commodity currencies and emerging market currencies, as investors shook off the credit crisis and piled back into risky assets. As a result, a widespread correction might be just what the doctor ordered, starting with the Australian Dollar.
By any measure, the Aussie was a standout in the forex markets in 2010. After getting off to a slow start, it rose a whopping 25% against the US Dollar, and breached parity (1:1) for the first time since it was launched in 1983. Just like with every currency, there is a narrative that can be used to explain the Aussie’s rise. High interest rates. Strong economic growth. In the end, though, it comes down to commodities.

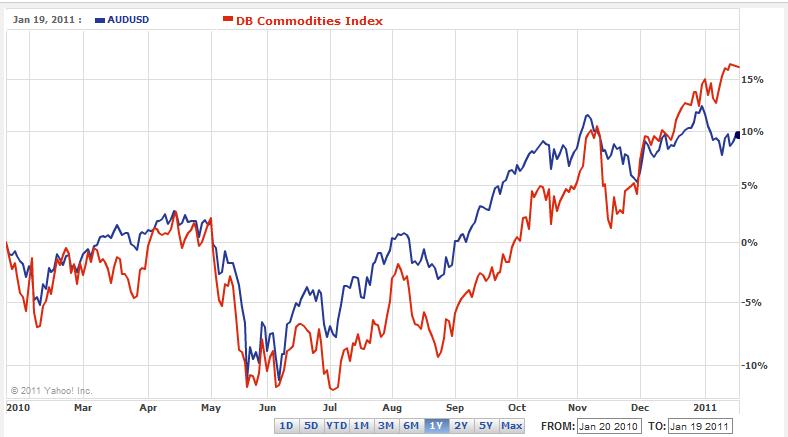
If you chart the recent performance of the Australian Dollar, you will notice that it almost perfectly tracks the movement of commodities prices. (In fact, if not for the fact that commodities are more volatile than currencies, the two charts might line up perfectly!) By no coincidence, the structure of Australia’s economy is increasingly tilted towards the extraction, processing, and export of raw materials. As prices for these commodities have risen (tripling over the last decade), so, too, has demand for Australian currency.
To take this line of reasoning one step further, China represents the primary market for Australian commodities. “China, according to the Reserve Bank of Australia, accounts for around two-thirds of world iron ore demand, about one-third of aluminium ore demand and more than 45 per cent of global demand for coal.” In other words, saying that the Australian Dollar closely mirrors commodities prices is really an indirect way of saying that the Australian Dollar is simply a function of Chinese economic growth.
Going forward, there are many analysts who are trying to forecast the Aussie based on interest rates and risk appetite and the impact of this fall’s catastrophic floods. (For the record, the former will gradually rise from the current level of 4.75%, and the latter will shave .5% or so from Australian GDP, while it’s unclear to what extent the EU sovereign debt crisis will curtail risk appetite…but this is all beside the point.) What we should be focusing on is commodity prices, and more importantly, the Chinese economy.
Chinese GDP probably grew 10% in 2010, exceeding both economists’ forecasts and the goals of Chinese policymakers. The concern, however, is that the Chinese economic steamer is now powering forward at an uncontrollable speed, leaving asset bubbles and inflation in its wake. The People’s Bank of China has begun to cautiously lift interest rates, raise reserve ratios, and tighten the supply of credit. This should gradually trickle down in the form of price stability and more sustainable growth.
Some analysts don’t expect the Chinese economic juggernaut to slow down: “While there is always a chance of a slowdown in China, the authorities there have proved remarkably adept at getting that economy going again should it falter.” But remember- the issue is not whether its economy will suddenly falter, but whether those same “authorities” will deliberately engineer a slowdown, in order to prevent consumer prices and asset prices from rising inexorably.
The impact on the Aussie would be devastating. “A recent study by Fitch concluded that if China’s growth falls to 5pc this year rather than the expected 10pc, global commodity prices would plunge by as much as 20pc.” [According to that same article, the number of hedge funds that is betting on a Chinese economic slowdown is increasing dramatically]. If the Aussie maintains its close correlation with commodity prices, then we can expect it to decline proportionately if/when China’s economy finally slows down.

Wednesday, June 29, 2011

Archive for the 'Australian Dollar' Category

Archive for the 'Australian Dollar' Category

Tide is Turning for the Aussie

“Australia is about to enter a boom that should last decades…The Australian dollar is unlikely to go back to where it was, and manufacturing will shrink in importance to the economy, perhaps even faster than it has been.” This, according to Martin Parkinson, Treasury Minister of Australia. While 30 years from now, Mr. Parkinson’s prognosis might probe to be accurate, I’m not so sure it applies to the period 3 months from now. Here’s why:
First of all, the putative economic boom that is taking place in Australia is being driven entirely by high commodity prices and surging production and exports. Since peaking at the end of April, commodity prices have fallen mightily. You can see from the chart above that there continues to exist a tight correlation between the AUD/USD and commodities prices. As commodities prices have fallen over the last two months, so has the Australian Dollar.


In addition, while demand will probably remain strong over the long-term, it may very well slacken over the short-term, due to declining economic growth across the industrialized world.  Consider also that Australia’s largest market for commodity exports – China – may have difficulty sustaining a GDP growth rate of 10%, and at the very least, new fixed-asset investment (which necessitates demand for raw materials) will temporarily peak in the immediate future.
Finally, the mining sector directly accounts for only 8% of Australia’s economy, which means that only to a limited extent to high commodities prices contribute to the bottom line of Australian GDP. This notion is reinforced by the 1.2% economic contraction in the second quarter – the biggest decline in 20 years – and the fact that GDP is basically flat over the last three quarters. Many non-mining economic indicators are sagging, and the number of corporate bankruptcies is 10% higher than in 2010. In the end, then, the ebb and flow of Australia’s fortune depends less on commodities, and more on other sectors.

Mr. Parkinson’s optimistic forecasts might also be undermined in the short-term by a looser-than-expected monetary policy. The Reserve Bank of Australia last hiked its benchmark interest rate in November 2010, and may not hike again for a few more months due to moderating economic growth and proportionally moderate inflation. Given that an attractive interest rate differential may be driving some of the speculative activity that has girded the Aussie’s rise, a decline in this differential could likewise propel it downward.
That’s because anecdotal reports suggest that the Australian Dollar remains a popular long currency for carry traders, funded by shorting the US Dollar, and to a lesser extent, Japanese Yen. Given that many of these carry trades are heavily leveraged, it wouldn’t take much to trigger a short squeeze and a rapid decline in the AUD/USD. For evidence of this phenomenon, one has to look no further back than May 2010, when the Aussie fell 10-15% in only three weeks.

Ultimately, as one commentator recently pointed out, the Aussie’s 70% rise since 2008 might better be seen as US Dollar weakness (which also catalyzed the rise in commodity prices). The apparent stabilizing of the dollar, then, might let some air out of the currency down under.


Tuesday, May 31, 2011

Aussie is Breaking Away from Kiwi

Aussie is Breaking Away from Kiwi
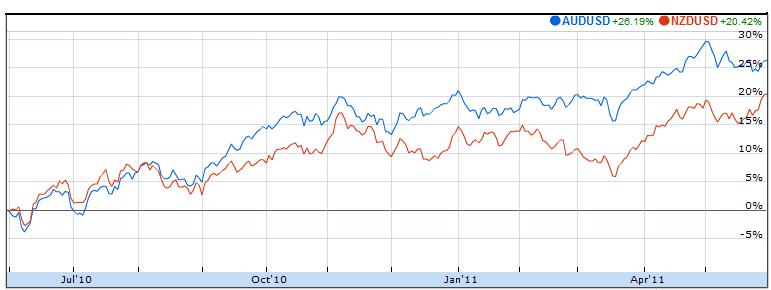
The correlation between the Australian Dollar and New Zealand Dollar is among the strongest that exists between two currencies. Given their regional bond and similar dependence on commodities to drive economic growth, perhaps this is no wonder. Over the last year, however, the Aussie has slowly broken away from the Kiwi. While the correlation between the two remains strong, the emergence of distinct narratives has given rise to a clear chasm, which can be seen in the chart below. Given that the NZD is evidently among the most overvalued currencies in the world, does that mean the same can be said about the AUD?

Alas, geographic proximity aside, the two economies have very little in common. Australia is rich in coal, precious metals and other natural resources , while New Zealand produces and export primarily agricultural products. Granted, the prices for both types of commodities have exploded over the last decade (and especially the last year), but let’s be clear about the distinction. This has enabled both economies to achieve trade surpluses, but oddly current account deficits. Australia’s economy is projected to grow by more than 4% in 2011, compared to 2% in New Zealand. Australia’s benchmark interest rate is also higher, its capital markets are deeper, and the supply of its currency necessarily exceeds that of New Zealand.
Taken at face value, then, it would seem commonsensical that the Aussie should rise both against the Kiwi and the US Dollar. Indeed, it recently touched an all-time high against the latter, and is now firmly entrenched above parity. On a trade-weighted basis, it has been among the world’s best performers over the last two years.
In fact, some are wondering (myself included), whether the Australian Dollar might have risen too much for its own good. According to OECD valuations based on purchasing power parity (ppp), the Aussie is now 38% overvalued against the dollar, behind only the Swiss Franc and Norwegian Krone. In fact, exporters of non-commodity products (i.e. those whose customers are actually price-sensitive) have warned of mounting competitive pressures, declining sales, and inevitable price cuts. In other words, the portion of the Australian economy that doesn’t deal in commodities is actually in quite fragile shape. Given that China’s economy is projected to slow over the next two years and that booming investment in Australia’s mining sector should boost output, the commodity sector of the economy might soon face similar pressures.
For that reason, the Reserve Bank of Australia (RBA) has avoided raising its benchmark interest rate is fast as some analysts had expected, and inflation hawks had hoped. There is a chance for a 25 basis point hike as soon as June – bring the base rate to an even 5% – but the RBA’s own statements indicate that it probably won’t be until June and July. Regardless of when the RBA tightens, Australian interest rate differentials will remain strong for the foreseeable future, and likely continue to attract speculative inflows for as long as risk appetite remains strong.
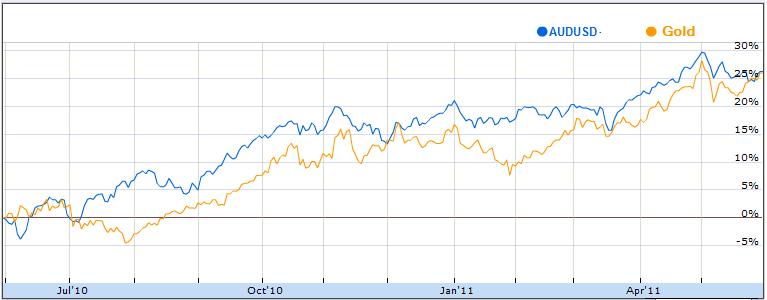
So why does the Australian dollar continue to rise? It might have something to do with gold. As you can see from the chart above, the correlation between the Aussie and gold prices is almost just as strong as the relationship between the Aussie and the Kiwi. Given that Australia is the world’s second largest gold exporter, it is perhaps unsurprising that investors would see rising gold prices as a reason for buying the Australian dollar. However, it seems equally possible that demand for both is being driven by the pickup in risk appetite. While some gold buyers might counter that gold is best suited for those who are averse to risk (i.e. afraid that the financial system will collapse), the performance of gold over the last five years suggests that in fact the opposite is true. When risk appetite is high, speculators have bought gold and the Australian dollar (among other assets).
It’s unclear whether this will remain the case going forward. The Wall Street Journal recently reported that gold is increasing attracting risk-averse investment, as buyers fret about the eurozone sovereign debt crisis and other threats to the system. However, the same cannot be said about the Australian Dollar. For as long as risk is “on,” demand for the Aussie will remain intact. And if the Aussie Dollar Barometer survey – which found that “exporters expect the Australian dollar to reach a post-float record of $US1.16 by September and to remain above parity well into next year” – is any indication, risk appetite will indeed remain strong for the foreseeable future.

Saturday, April 2, 2011

Can the Australian Dollar Hold on to Record Gains?

Can the Australian Dollar Hold on to Record Gains?
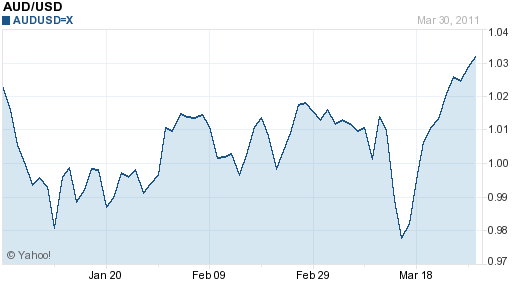
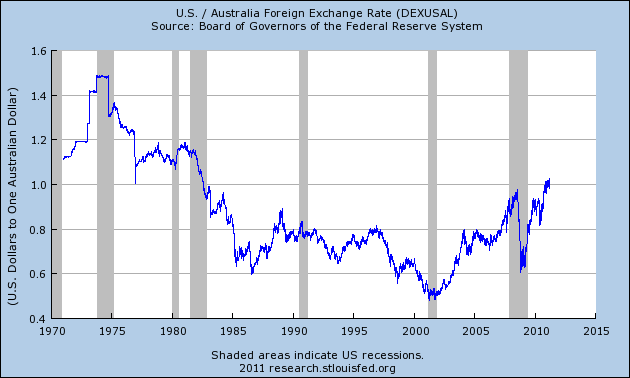
The volatility of the last couple weeks has manifested itself in some unbelievable outcomes. In this post, I want to focus specifically on the Australian Dollar. When the Japanese disasters struck, the Aussie immediately tanked, as investors jettisoned risk and moved towards safe haven currencies. Only days later, it inexplicably rose 5%, en route to parity and a 28-year high against the US Dollar. The question is: will the Aussie hold on to these gains, or will it return to earth as soon as the markets come to terms with the misalignment with fundamentals?


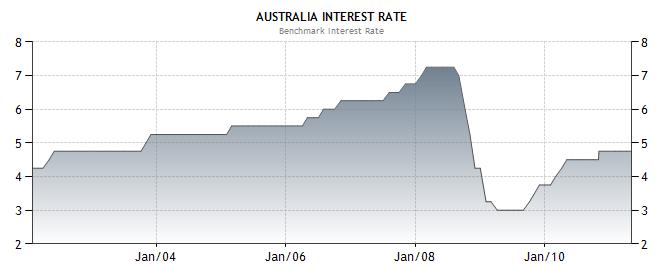
The Australian Dollar remains buoyant largely because of interest rate differentials. Basically, Australia boasts the highest benchmark interest rates (4.75%) in the industrialized world, and investors are betting that it will rise further, perhaps to 5.5% by the end of 2011 and even higher in 2012. Given that the other G7 Central Banks probably won’t hike for a couple more quarters – and even then, rate hikes will be gradual and restrained – it’s only natural that yield seekers are flocking to the Aussie.
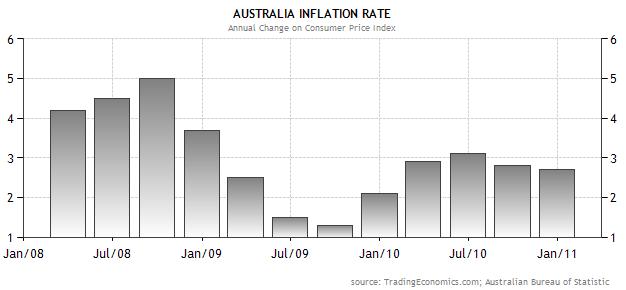
However, it seems possible that the markets have gotten ahead of themselves in presuming an airtight case for further rate hikes. While Australian inflation is somewhat high (2.7%), it has actually moderated slightly over the last six months. In addition, the rising Australian Dollar will help to mitigate inflation and hence make it less likely that the Reserve Bank of Australia (RBA) will hike rates. (How ironic that the markets’ bet on higher interest rates in Australia actually makes it less likely that those rate hikes will actually take place!).

Moreover, the domestic Australian economy isn’t performing as well as some people think. It is true that an investment boom in mining and a surge in commodities prices have provided an economic windfall. On the other hand, the strong Aussie has undermined strength in the manufacturing sector, the housing market is poised for correction, and the summer flooding will crimp at least .5% from 2011 GDP.
In fact, not only is it not guaranteed that the RBA will hike rates, but some analysts think it’s possible that the RBA will cut its benchmark cash rate before the end of the year. At the very least, analysts need to double check their assumptions and re-jigger their interest rates models.  Given that the Australian Dollar is primarily being supported by expectations for higher interest rates, that also means that investors to scale back their forecasts for the Australian Dollar.
Personally, I think that a bubble is beginning to form in currency markets, at least in certain corners of it. Due to commodity prices and relatively high interest rates, the Aussie is certainly one of the more attractive major currencies at the moment. At that same time, that it has risen so fast in the last few years – and especially in the last few weeks – strikes me as fundamentally illogical. At this point, its rise has become self-fulfilling; investors want it to rise, and so it does.
At this point, there are two possibilities. Either the markets will wait for fundamentals to catch up with the Aussie, and it will hover around parity or appreciate slightly, or investors will recognize that it has appreciated too much too fast, and its correction will become one of the major events in forex markets in 2011.

Saturday, October 16, 2010

Betting on China Via Australia

Betting on China Via Australia
There are plenty of investors that think betting on China is as close to a sure thing as there could possibly be. The only problem is that investing directly in China’s economic freight train is complicated, opaque, and sometimes impossible. The Chinese government maintains strict capital controls, prohibits foreigners from directly owning certain types of investment vehicles, and prevents the Chinese Yuan from appreciating too quickly, if at all. For those that want exposure to China without all of the attendant risks, there is a neat alternative: the Australian Dollar (AUD).

Those of you that regularly read my posts and/or follow the forex markets closely should be aware of the many correlations that exist between currencies and other financial markets, as well as between currencies. In this case, there would appear to be a strong correlation between Chinese economic growth and the Australian Dollar. If the Chinese Yuan were able to float freely, it might rise and fall in line with the AUD. Since the Yuan is fixed to the US Dollar, however, we must look for a more roundabout connection. HSBC research analysts used Chinese electricity consumption as a proxy for Chinese economic activity (why they didn’t just use GDP is still unclear to me), and discovered that it fluctuated in perfect accordance with the Australian Dollar.
Australian Dollar and Chinese electricity consumption 1990-2008
Before I get ahead of myself, I want to explain why one would even posit a connection between China and the Aussie in the first place. There are actually a few reasons. First, Australia is economically part of Asia: “Today, 43 per cent of Australia’s total merchandise trade is with north Asia. A further 15 per cent is with Southeast Asia.” Second, Australia’s economy is driven by the extraction and sale of natural resources, of which China is a major buyer and investor: “In 2008-9, China was the biggest investor in the key resource sector with $26.3bn involvements approved, 30 per cent of the total.” Third, Chinese demand has come to dictate the prices of many such resources, causing them to rise continuously. Thus, Australia’s natural resource exports to countries other than China still draw strength (via high commodity prices) from Chinese demand.
As one analyst summarized, “China is buying raw materials from Australia in leaps and bounds, and that’s what’s driving that currency’s growth.” Sounds like an Open and Shut case. In fact, this presumed correlation has become so entrenched that any indication that China is trying to cool its own economy almost always prompts a reaction in the Aussie. To be sure, warnings that China’s annual legislative conference (scheduled for October 17) would produce a consensus call for a tightening of economic policy have made some forecasters more conservative. Still, as long as the Chinese economy remains strong, the Australian Dollar should follow.
It’s worth pointing out that the correlation between the Aussie and the Chinese economy doesn’t exist in a vacuum. For example, the Australian Dollar has also closely mirrored the S&P 500 over the last decade, which suggests that global economic growth (and higher commodity prices) are as much of a factor in the Aussie’s appreciation as is Chinese economic activity. The Aussie is also vulnerable to a decline in risk appetite, like the kind that took place during the financial crisis and flared up again as a result of the EU Sovereign debt crisis. During such periods, Chinese demand for commodities becomes irrelevant.
AUD USD 2006-2010
On the other hand, part of the reason the Australian Dollar has surged 10% since September and 20% since June is because other countries’ Central Banks (such as China) have increased their interventions on behalf of their respective currencies. Australia is one of a handful of countries whose Central Bank not only hasn’t actively tried to depress its currency, but whose monetary policy (via interest rate hikes) actually invites further appreciation. As the Aussie closes in on parity and Australian exporters and tourism operators become more vocal about the impact on business, however, the Reserve Bank of Australia (RBA) might be forced to act.